Borrow against your equity. Keep your low mortgage rate.
A Home Equity Line of Credit (HELOC) gives you a reusable revolving credit line up to $500,000. Draw only what you need, pay interest only on what you use, and keep your existing low-rate first mortgage 100% intact.
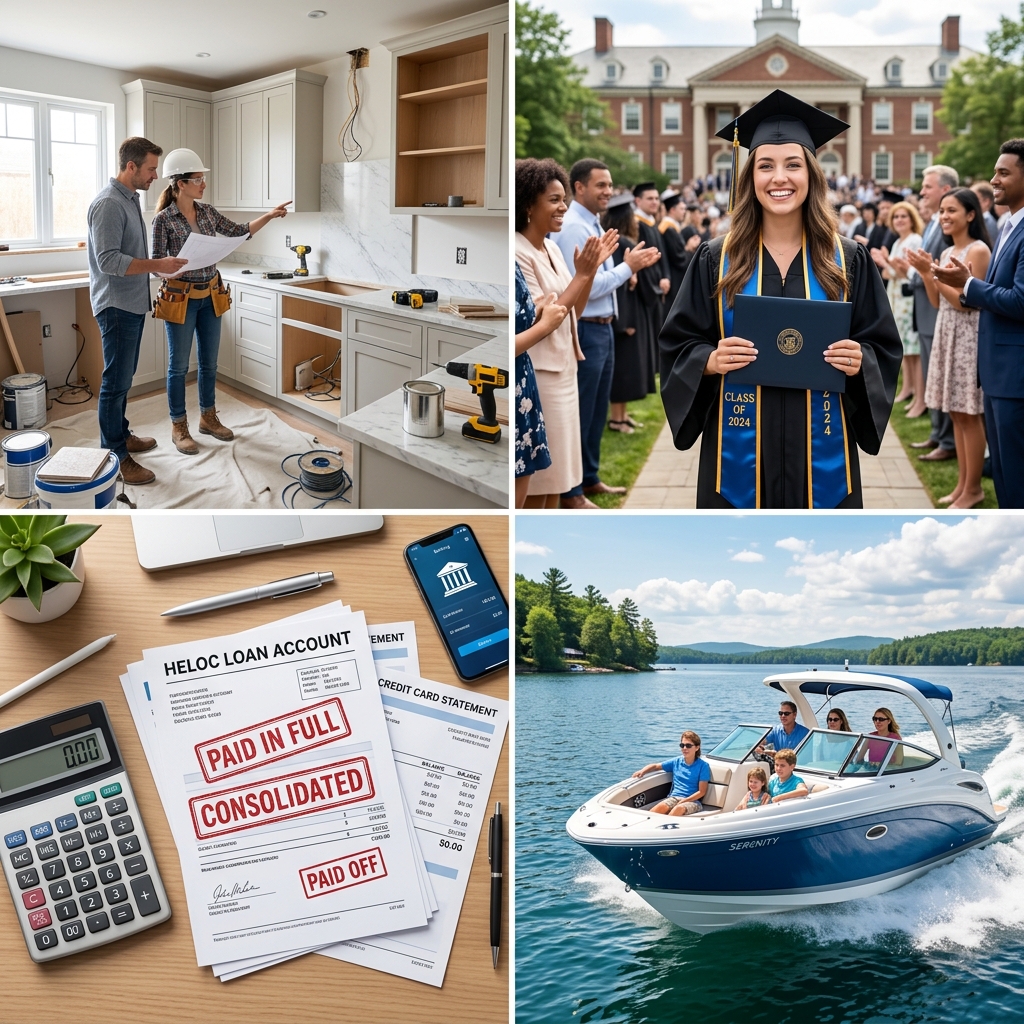
Revolving credit. Flexible draw.
No refinance.
Unlike a traditional second mortgage, a HELOC works like a credit card — providing a revolving line of credit you draw on as needed.
Draw Period (10 Years)
Access your funds on-demand as needed during the initial 10-year draw period.
Pay Only What You Use
Only pay interest on the amount you actually draw, not your entire limit.
Rebuilding Credit Line
As you pay back the principal, your available credit line restores automatically.
Repayment Period (20 Years)
Pay back the remaining balance over a structured 20-year repayment term.
Why an OptionOne HELOC makes sense.
Access to Cash
Use funds for home improvements, debt consolidation, or other financial needs.
Fixed or Adjustable Borrowing
Withdraw only what you need, when you need it.
Lower Interest Rates
HELOCs generally have lower interest rates compared to credit cards or personal loans.
Potential Tax Benefits
Interest on a HELOC may be tax-deductible if used for home improvements (consult a tax professional).
Frequently asked questions.
A HELOC can be used for home improvements, debt consolidation, education expenses, emergency funds, or as bridge financing while waiting to sell a current property — with zero restrictions on how you access your funds.
Qualification typically requires sufficient home equity, a credit score of 620+ (higher credit tiers unlock lowest rates), a debt-to-income (DTI) ratio up to 50%, and verifiable income. OptionOne offers both Full Doc (W-2s/tax returns) and alternative Bank Statement qualification for self-employed homeowners.
A HELOC works like a revolving credit card: you borrow only what you need, pay interest only on what you use, and redraw during the 10-year draw period. A fixed second mortgage provides a single lump sum of cash at closing with a predictable fixed monthly payment for the entire term.
Interest on a HELOC may be tax-deductible if the borrowed funds are used to buy, build, or substantially improve the primary or secondary home that secures the credit line. Always consult your CPA or tax professional for advice on your specific tax situation.
OptionOne provides HELOC revolving credit lines up to $500,000, with Combined Loan-to-Value (CLTV) ratios reaching up to 90% of your property's appraised value — all without touching your primary first mortgage rate.
Ready to access your home equity?
Up to $500k, 90% CLTV. Tap your equity without refinancing.